Newsletters - Past Issues

Inflation Will Continue UPDATE September 14 2026


The age old inflation hedge


-----> GOLD <-----


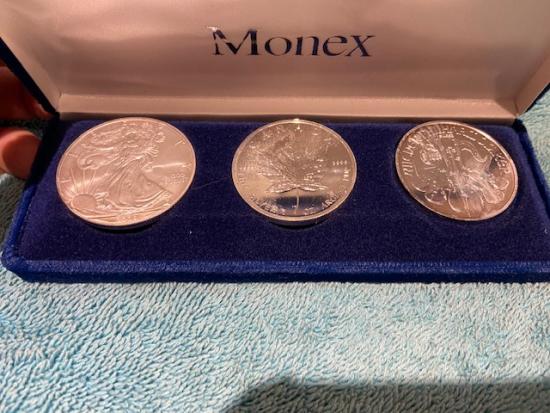
Coins and bars from a friend's family trust now available for a limited time until they are gone

Reserve yours now by calling  (530) 559 1214


The middle east crisis continues and oil spiked north of $100/bbl. last week. A client of mine showed me a report on the gasoline supplies in various areas of the United States and it was not encouraging.

Petroleum Reserve crude inventories fell to 311.45 million gallons in the week ending July 17, which is the lowest level since 1983.

With inflation’s relentless climb since the Covid shutdowns, doing the math on the money created to finance the massive bailouts, I am of the opinion that the price of oil will not come down significantly any time soon.

I would say “if at all” as it relates to oil’s future price, but knowing the resilience of the oil industry, if not constrained, it can ramp up enough production to at least get the price back under $100/bbl. and perhaps even in the $80/bbl. range.

Any lower than that I think is out of the question as the inflation we have been experiencing since Covid is baked into the cake and therefore prices of everything will stay elevated for years to come.

Barring an economic collapse that is, which could happen, given the ongoing erosion of the consumer’s pocketbook due to the same inflation.

Not to be too negative mind you, but prices have always risen over time since about the 1900’s due to the policies of modern governments, and the latest round of inflation in the past few years has been particularly egregious.  

Tariffs are estimated to have added 235 billion to retail costs. The increase in oil prices has done further damage to consumer pocketbooks. Covid bailouts dwarf the latter costs at an estimated 5 trillion. The Federal Reserve also increased its balance sheet by an estimated 4.5 trillion. That’s a fancy way to say it financed a good portion of that bailout money by creating dollars out of thin air.  More monies went into financial `system` to address liquidity concerns that also occurred because of the shutdowns. 

Can you say bank bailout?

Right or wrong, experts will certainly debate the whys and how’s of the whole mess for years to come.

Subsidies to both consumers and businesses alike have pretty much run the gamut since the 1960s’ and show no signs of stopping.

Whether one agrees with subsidies to either group is highly debated but the effects are clear. Government spending that exceeds government income is known as deficit spending. Most, if not all governments of the world, practice deficit spending on a grand scale. 

And the scale gets grander seemingly every year.

As such, inflation is accelerating and this analyst sees no relief to that acceleration.

On many of my past radio shows, I often ended many economic discussions with “You ain’t seen nuthin’ yet.”

And sadly, once again, I am afraid you still haven’t.

“Watching the markets so you don’t have to”


This article expresses the opinion of Marc Cuniberti and is not meant as investment advice, or a recommendation to buy or sell any securities, nor represents the opinion of any bank, investment firm or RIA, nor this media outlet, its staff, members or underwriters. Mr. Cuniberti holds a B.A. in Economics with honors, 1979, and California Insurance License #0L34249 His insurance agency is BAP INC. insurance. 


Vision, Dental and Hearing Care here:

https://myplan.ameritas.com/id/010X1426
One of the easiest website to get a quote ever!


Inflation and those high priced yoga mats Update September 5 2026


Why not?
Because they COST TOO MUCH


Last week I was watching my usual business channel, and they were discussing the recent hammering of the clothing manufacturer Lululemon’s stock. The analysts were blaming the drop in their stock by anemic marketing, unexciting products and better execution by their competitors like Nike and others in the sports clothing space. The discussion centered around which of their competitor’s stock would they buy instead of the foundering stock of Lululemon.

Sorry kids. I couldn’t disagree more. The problem is not with Lululemon per se and the investing solution is not in the buying of some other upper tier clothing company’s stock.

Let’s just back up a bit shall we and open up our ECON 101 books once again.

It’s surprising that many of the commentators featured on business channels keep missing the basics when it comes to macro-economic analysis.

Lululemon, Nike and some of the other sports clothing lines exist in what I would call the highly discretionary apparel space. This means the price is higher than some of the other retailers that supply athletic clothing.

Puma, Nike, Under Armour and Adidas have all had their stocks drop in price in the last year or so and it isn’t because one company or another has been doing a better job of it.

The fact of the matter is that all these companies sell high-end apparel, and people just can’t afford to spend $80 on a yoga mat or $160 on a pair of sneakers when there are cheaper options available.

As the TV analysts argued over which high end clothing stock they would buy instead of Lululemon, I sat screaming at the screen saying, “None of them!”

Sure, Lululemon might be making some mistakes as compared to its competitors, but that’s not the issue. The whole high end clothing space, indeed, many of the high-end retailers, no matter what they’re selling are finding fewer and fewer customers that can afford higher priced items when cheaper alternatives are plentiful.

It doesn’t take a rocket scientist to know why these companies are struggling. It’s because of the persistent and aggressive inflation that has been ongoing since the end of the CoVid shutdowns.

I am sure most of you reading this knew that answer already, right?

Massive amounts of CoVid bailout money combined with the end of the shutdown demand met with the constricted supply lines of the very same shutdowns which has spawned the worst inflation since the 1980’s. Add to that the ongoing tariffs and the spike in oil prices and it makes for an inflationary fire that continues to rage on seemingly without let up.

Adding insult to inflationary injury, I read a new wrinkle in the prognostication of inflation centering around Artificial Intelligence (AI). There have been several articles by Reuters, CNBC and even the Federal Reserve citing that the cost in AI will force up overall prices even further.

The basic premise came about by observing the humongous run up in AI stock prices. The investment by many companies to incorporate AI in their services has been huge, close to a trillion dollars this year alone. Estimates on future spending reaches into the multitrillions.  

Since this massive spending adds to the cost of production of almost all goods and services, those costs will be passed onto the consumer in the way of higher prices.

I keep saying inflation will not be going away anytime soon, or anytime later either.

I also keep saying, “You ain’t seen nuthin’ yet”.

And you ain’t.

“Watching the markets so you don’t have to”

 This article expresses the opinion of Marc Cuniberti and is not meant as investment advice, or a recommendation to buy or sell any securities, nor represents the opinion of any bank, investment firm or RIA, nor this media outlet, its staff, members or underwriters. Mr. Cuniberti holds a B.A. in Economics with honors, 1979, and California Insurance License


Medicare

Dental care

Vision care

Hearing 


ALL AFFORDABLE    Contact me here  (530) 559-1214


When to Buy or Sell Stock Update Aug 17 2026


My father was an unusual investor with unusual tactics. He would read some investing book somewhere and fall hook, line and sinker into the story. His big one was buying silver in the late 1970’s. Silver had sat around four bucks an ounce for seemingly forever and the book he was reading blew the usual horns that hot investor books blow.

Silver was in short supply. The mega-banks were reportedly heavily “shorting” it (selling silver to bring and keep the price suppressed). It was about to explode in price touted the book and would go up by many multiples.

Dad bought thousands of dollars’ worth and even though it languished, he kept buying more. When the price finally did move, he bought more and more and his profits doubled, then tripled, then quadrupled. He amassed many millions from a few hundred thousand and still kept buying.

However much me made, his eyes kept getting bigger and used the silver he owned as leverage to buy even more.
I don’t recall how many ounces he amassed or how many millions he had made, but he never sold nary an ounce.

To make a long story short, the folks at the big banks who were on the losing side of the trade convinced the FED that the rise was something akin to an unnatural act and the exchanges that traded the stuff were instructed to act.

Or so the story goes.

In any case, through more than a handful of questionable and rumored to be illegal acts by the “big boys”, silver came crashing down and my father’s money vaporized right along with it.

The moral of the story here is no investment is without risk, and not selling at least some of one’s investing winners is often a recipe for disaster.

In my experience, investors may frequently err on the side of buying their way out of good times as well bad times.

What I mean by this is I often see investors buying more of their losing stocks, averaging the price of their shares by buying more at lower prices.

Interestingly enough, they will use the same strategy on their winning stocks. As their stocks go up and they see more profits, they will also buy more shares in this direction as well.

Think about that one for a minute. The same strategy used for losing stocks is also used for winning stocks.

Sounds counterintuitive, doesn’t it?

And in my opinion, with few exceptions, makes little sense.

The two most descriptive and, in my opinion, dangerous words in the investing mind is fear and greed.

Although fear generates the selling act, the buying of both losing and winning stocks is based almost exclusively on greed.

My dad’s downfall was greed. Whatever he made, it was never enough. When he reached a million, he imagined two million. When he reached two million, he imagined five. And so on and so forth.

He probably could have got to 100 million and still would have set his sights on many millions more.

On the flip side, buying more of a losing stock is also driven by the same emotion. Belief in a stock is not negated by a falling price. Instead, the belief remains even more so. The allure of buying more stock at an even cheaper price activates the calculator of the mind and the profit possibilities becomes even more grandeur.

Many investors know of whence I speak and may, even now, resist the lesson that many a pro trader knows all too well.

Don’t chase your losers and take some profits on your winners.

Doing the flip side of that is often an expensive and painful lesson.

“Watching the markets so you don’t have to”

(end)    

(As mentioned, please use the below disclaimer exactly) THANKS   (Regulations)   This article expresses the opinion of Marc Cuniberti and is not meant as investment advice, or a recommendation to buy or sell any securities, nor represents the opinion of any bank, investment firm or RIA, nor this media outlet, its staff, members or underwriters. Mr. Cuniberti holds a B.A. in Economics with honors, 1979, and California Insurance License #0L34249 His insurance agency is BAP INC. insurance services.  Email: news@moneymanagementradio.com.


CAL FAIR FIRE INSURANCE RATES TO RISE 29.1% IN 60 DAYS! OUCH UPDATE 2026


CAL FAIR JUST ANNOUNCED A 29.1% RATE INCREASE STARTING IN OCTOBER


Those Car Warranties HOW WHY WHEN Update Aug 8 2026


'Breakdown?
Wonder if my car warranty will cover this!


Buying an automobile is one of the largest investments a person can make outside of buying a home. I have written many articles on how to buy both a new and used car, but today’s musing will delve into how to deal with car warranties, and which ones are worth considering.

Years back, when I was a kid, just about anyone could work on a car and be somewhat successful at it with a little bit of research and practice. Warranties were basically protecting a buyer against major failures and the little nitpicky malfunctions in the first 12 months of purchase. There were few if any opportunities back then to buy an extended warranty. This, along with the simple sticker price, made buying a car an easy, semi-affordable and understandable task.

Not so nowadays.

The sticker price has been replaced by the “payment”, car warranties run the gamut from free to many expensive options and there are now extended terms that may cover the car for many years. The cars also have gotten much more complicated, with multiple onboard computers and black boxes that make servicing a car much more difficult for the average garage’ tinkerer.

Replacement parts seem to have skyrocketed in price and if a car is newer, aftermarket parts may or may not be available for many years or if at all. I won’t go into all the gory details about why that is. Just know not all parts for all cars can be bought on the cheap at your local auto parts store.

In addition, many auto repair shops must specialize in only certain manufacturers in order to avoid learning about the workings of many different cars. Different cars can require different skill sets, tools and/or diagnostic equipment, further limiting our choices as consumers and therefore driving up costs in the process.

I have thought, more than a few times, that repairing a car that is out of warranty has become too expensive to not consider wrapping each and every car I now buy into some sort of warranty. But not just any warranty, mind you.

I flatly refuse to buy an after-market or extended warranty that is not from the original manufacturer of the automobile.

I have heard too many tales of woe from people who have purchased those private aftermarket warranties. Their slick ads lead consumers into paying a ton of money for a generic warranty only to find out there are many exceptions, caveats and conditions to these products which basically work in favor of the warranty company and not you.

When buying a new car, you obviously get a warranty but the option to extend it might be considered at time of purchase. No doubt, they are expensive. But those extended warranties are cheaper at the time you buy the car. Waiting can only drive up the cost of extended warranties due to inflation and locking in the manufacturer at time of purchase might be worth considering. You might also be able to wrap the warranty into the payment making it that less painful.

If buying used, again, I would stay away from any warranty product not offered by the original manufacturer of the car. I would also recommend you consider paying a little more for a “Certified” used car from a manufacture’s dealer and not from some random “car lot” somewhere.

I know a certified car from a manufacturer’s dealer may run you a few dollars more. Maybe even a few thousand more. But one random repair can still run into the thousands. I remember some years ago my Toyota Sienna van had the electric side door motor go out. That tiny motor was like four thousand dollars if memory serves me right.

Yikes. Lucky, I had purchased an extended warranty.

In conclusion, we may be at the point where the car manufacturers have us in a big “gotcha” moment where repairing a car is so expensive, the cars just become big throwaways that end up on one in one of those random used car lots somewhere. Then some unfortunate buyer will probably get stuck with a humongous repair bill that you avoided by dumping the car on the cheap.

It starts to make little sense buying a newer car without a warranty.  If something major goes wrong, or maybe even something minor, the cost of repairing it could more than offset the cost of buying an older car without a warranty to save some money.

If you are buying a substantially older car with fewer bells and whistles that your local repair shop perhaps can work on, so be it. But if you are looking at something more recent, it might be wiser to get a car protected by the original manufacture, no matter how that is accomplished.

The car companies have gotten smart. They have made repairing a used car so expensive, you have to buy a new one.

And isn’t that just grand.

For them.

  This article expresses the opinion of Marc Cuniberti and is not meant as investment advice, or a recommendation to buy or sell any securities, nor represents the opinion of any bank, investment firm or RIA, nor this media outlet, its staff, members or underwriters. Mr. Cuniberti holds a B.A. in Economics with honors, 1979, and California Insurance License #0L34249 His insurance agency is BAP INC. insurance services.  Email: news@moneymanagementradio.com.


VISION  DENTAL  HEARING PLANS 

LOW COST   EASY TO GET A QUOTE

LINK HERE:

https://myplan.ameritas.com/id/010X1426